Global air freight rates dip 2.1% as peak season approaches
Rising jet fuel prices and tight capacity could push rates higher, while European outbound rates continue to strengthen across key trade lanes.
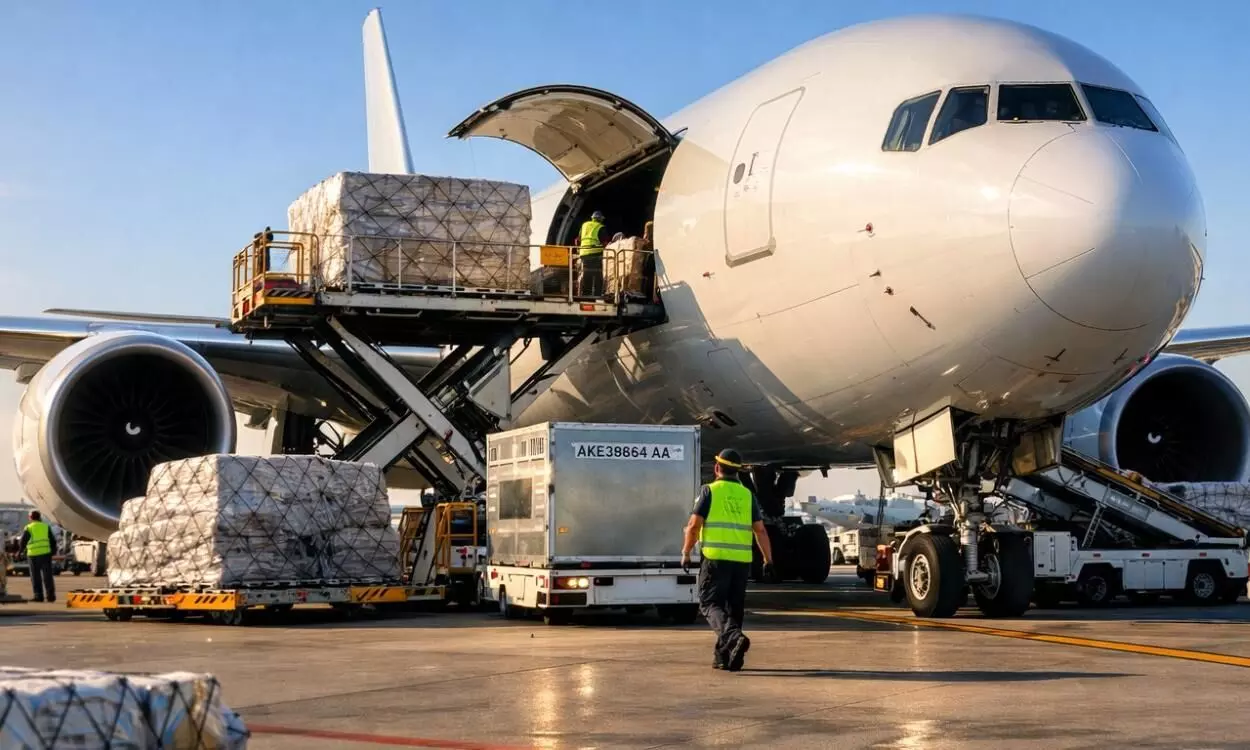
Global air freight rates fell 2.1% in the seven days to October 12, 2026, according to the latest data from TAC Index. Despite the decline, the global Baltic Air Freight Index (BAI00) remained 24.3% higher year on year, with market sources indicating that rates could rise as the traditional peak season approaches.
The slight decline was in line with the usual slowdown during China's Golden Week holiday, when factories often close and cargo volumes decrease. However, market sources said conditions remained firm as e-commerce companies and other major shippers had secured capacity for the peak season. Some shippers, including AI hyperscalers, were yet to secure space, which could put further upward pressure on rates.
Jet fuel prices also continued to rise. The IATA Jet Fuel Price Monitor recorded a 3.1% week-on-week increase to October 9, taking prices 111.2% higher year on year.
Rates on major routes from China to Europe and the US declined slightly week on week. However, most spot rates from Hong Kong, Shanghai and South Korea increased, particularly in recent days.
The overall index of outbound routes from Hong Kong (BAI30), which covers spot and forward contract rates, rose 0.2% week on week and remained 20.5% higher year on year. The Shanghai outbound index (BAI80) fell 2.1% week on week but also remained 20.5% higher year on year.
Rates from other East Asian markets mostly increased, including routes from Taiwan, Japan to Europe and Seoul to the US. In South East Asia, rates from Bangkok rose week on week, while rates from Vietnam to Europe declined.
Air freight rates from India also fell slightly week on week but remained significantly higher year on year. Spot rates from India remained firm, and market sources reported that capacity was expected to remain tight.
Rates from Asia to Europe remained weaker overall than those on intra-Asia and Transpacific routes. However, sources reported an increase in Europe-to-US pass-through business.
Outbound rates from Europe strengthened further, with week-on-week increases on Transatlantic routes to the US and routes to China, India, Australia and South Africa. Rates declined modestly on routes to Japan, Mexico and the UAE.
The Frankfurt outbound index (BAI20) rose 3.0% week on week to stand 47.7% higher year on year. The London Heathrow outbound index (BAI40) increased 12.1%, supported by gains on routes to North America and the Middle East, and remained 44.7% higher year on year.
In North America, rate movements were mixed. Rates increased on routes to South America, led by a sharp rise on southbound routes from Miami, and on routes to Europe. However, rates declined on routes to the UK, China and South Korea.
After recent strong gains, the Chicago outbound index (BAI50) fell 29.0% week on week, mainly due to sharp declines on routes to Asia. Despite the drop, it remained 15.6% higher year on year.
Rates from Mexico to Europe also declined slightly week on week but remained well above year-earlier levels.