

Asia to North America: The lane that chips built
AI hardware has turned Asia–North America into air cargo’s hottest lane, just as war, fuel costs and shifting tariffs are squeezing the space they fight over.
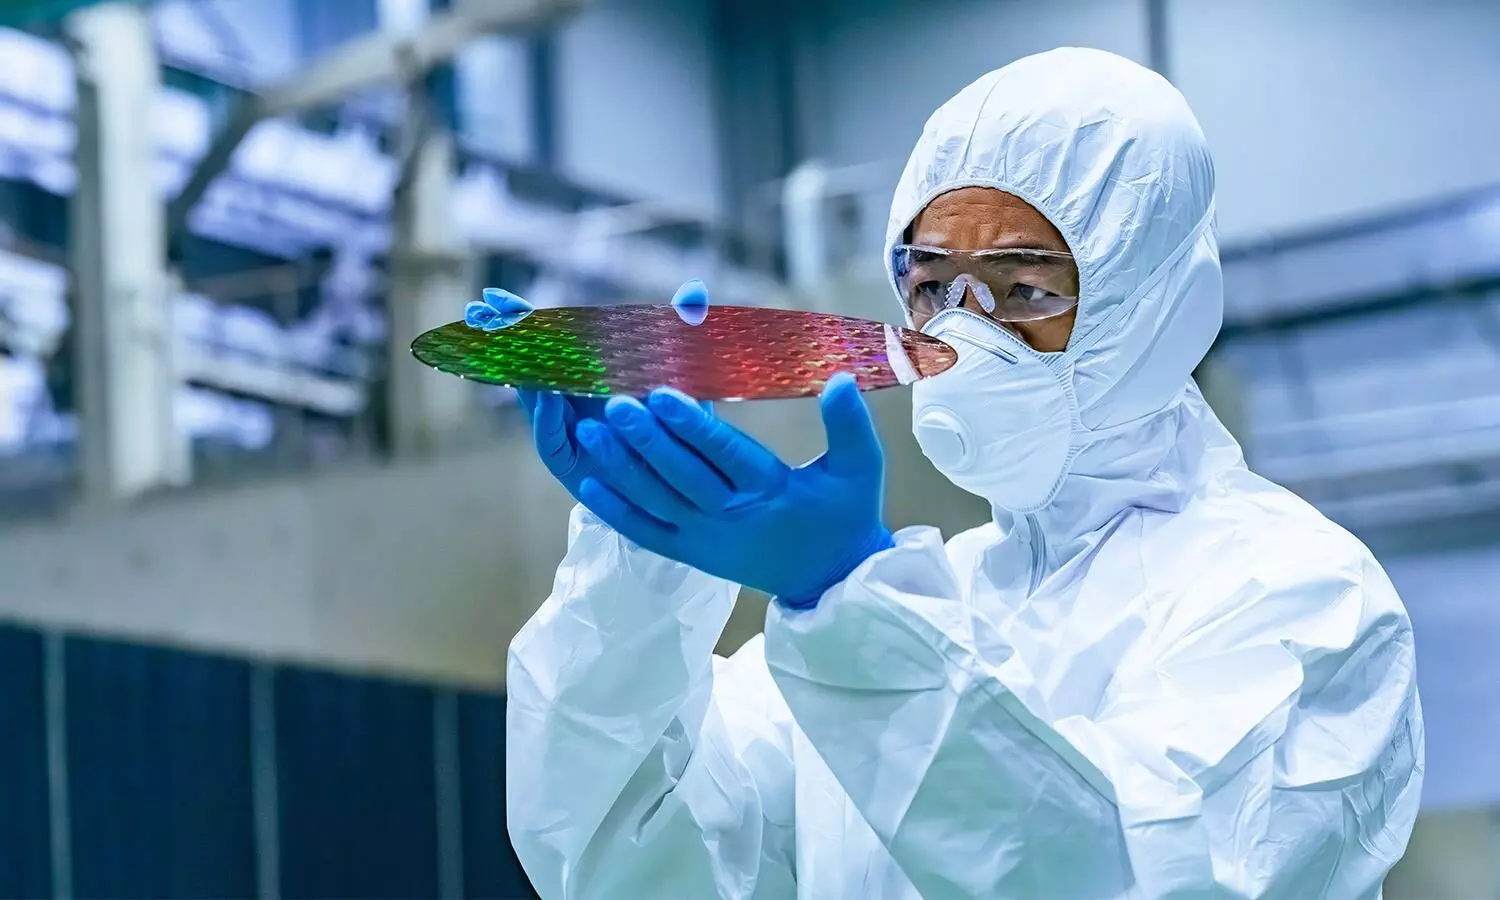
Not long ago, the freighters crossing the Pacific were packed with the parcels of the e-commerce boom: fast fashion, phone cases, gadgets bound for doorsteps across America. Today, a growing share of that main-deck space belongs to cargo that looks far duller and is worth far more: the servers, processors and networking gear being rushed into the data centres that artificial intelligence runs on.
The numbers explain the shift. IATA’s latest figures show Asia–North America as the strongest major trade lane in August, with demand up 13.2% year on year, its seventh consecutive month of growth. The lane now accounts for 23.5% of industry traffic. In the same month, global demand rose 4.4% on capacity that was essentially flat.
That gap between runaway demand and constrained supply is the story of the year in air cargo. Network resilience, supply-chain agility and the pace of digital change are all being tested at once, and nowhere more than on the transpacific.
$180 Million, Priceless Payload
Meet the machine that makes AI’s brains. ASML’s Twinscan NXE:3800E extreme ultraviolet lithography system, priced at about $180 million, mass-produces the 2nm logic and leading-edge DRAM chips that power artificial intelligence. It is dismantled in Veldhoven, crated, and flown on several freighters to chip foundries in Taiwan, Korea and the US. Few cargoes carry higher stakes. (Photo: ASML)
From parcels to processors
The easy assumption is that AI has taken over air cargo. The data is more subtle. Xeneta estimates that AI-related goods make up less than 10% of global air cargo volumes, but they are concentrated on transpacific services, which has made the lane the market’s strongest performer. Niall van de Wouw, Xeneta’s chief airfreight officer, puts it plainly: “While e-commerce demand is cooling, AI-driven freight is booming, particularly on the Transpacific.” The upstream signal is striking: Xeneta points to global semiconductor sales that rose 106% year on year in April, the sharpest jump on record.
WorldACD’s weekly data shows how this plays out at origin level. In the week of 21 to 27 September, tonnage from Asia Pacific to the United States was up 14% on a year earlier, and the average rate was 38% higher. Volumes out of Vietnam, Malaysia, Taiwan and Singapore climbed between 6% and 12% week on week, partly on AI-related traffic.
The map of origins is changing too. In mid-September, WorldACD recorded year-on-year gains to the US of 26% from Singapore and 33% from Indonesia. Cathay Cargo’s James Evans told STAT Times that the strongest AI flows now link Southeast and Northeast Asia with the Americas, and that the China+1 manufacturing shift has accelerated sharply in the past year. Dimerco’s October report describes air space to the US as tight from most Asian origins, with Singapore at backlog and Taiwan’s rates rising on AI and semiconductor exports.
The tightness is concentrated where the chips are made. Dimerco’s October forecast rates air space from Taiwan to both US coasts as tight with rising rates, driven by AI servers, semiconductors and high-performance computing equipment. From China, by contrast, it sees US-bound capacity as picking up but still meeting demand, with stable rates, and says South China e-commerce is softening on cautious Black Friday stocking while electronics and semiconductors hold volumes up. Freightos data this month showed Southeast Asia–North America rates roughly 40% above a year ago, a gap it attributes in part to data-centre volumes.
“While e-commerce demand is cooling, AI-driven freight is booming, particularly on the Transpacific.”
Niall van de Wouw, Xeneta
The freighter pendulum
If demand explains the transpacific’s strength, capacity explains its tension, and the picture has swung dramatically within a single year.
In January, Aevean’s data showed airlines drifting away from the lane: freighter capacity from Asia to North America was down 9% year on year, while Asia–Europe freighter capacity jumped 31%. Europe’s e-commerce corridor was where the aircraft wanted to be.
Then policy intervened. As the EU tightened its treatment of low-value parcels, that demand base eroded and the aircraft moved. DHL reports China–Europe freighter capacity down roughly 30% since June, pushing Asia–US load factors towards 90%. Aevean calculated that daily freighter capacity from Asia Pacific and the Middle East and South Asia into Europe fell 14% in July against June, the equivalent of about 18 fewer widebody freighter flights a day. WorldACD read the same signal in August, suggesting that freighters once flying e-commerce to Europe had been redeployed to the transpacific.
The squeeze shows at the gateways. Dimerco’s October report says peak season is running long in North America, with air tightening on AI, semiconductor and retail cargo. Los Angeles and San Francisco anchor transpacific flows, and Chicago O’Hare carries backlog risk.
Even so, supply is hemmed in. IATA recorded global capacity down 0.1% in August, and Xeneta put September growth at 2%. Aevean’s delivery projections add an irony: roughly half of 2026’s new widebody capacity is headed for Middle East operators, some 1.7 million tonnes against 0.6 million for North America, into a region whose network is still recovering from conflict.
War, fuel and a fragile map
No account of 2026 can ignore the Middle East. The escalation of 28 February removed an estimated 12% of global air cargo capacity almost overnight, according to Xeneta, holding first-half supply growth to just 1% while demand grew 4%. Rotate’s live data showed global capacity down 18% week on week within 24 hours of the first suspensions. Combined spot and contract rates rose 17% year on year in the first half. The estimates differ because capacity is measured differently by different providers, but the direction is not in dispute.
Fuel compounds the pressure. IATA reports jet fuel was 79.2% more expensive in August than a year earlier, and Xeneta noted Brent crude passing $100 a barrel in early September. Recovery remains incomplete: IATA says Gulf-linked corridors are still disrupted, WorldACD put Gulf-area capacity 16% below its pre-conflict level in mid-September, and attacks on Saudi airports have disrupted operations again this month.
Ocean disruption adds a second claim on the same scarce lift. After the first-half shock, air charters were back within days while ocean services were only beginning to move again through Hormuz, reinforcing air’s role as the fallback. Dimerco’s October report expects more cargo to convert from ocean to air on transpacific and intra-Asia lanes through the fourth quarter, citing port congestion it calls worse than during the pandemic and ocean rates back near pandemic levels. Xeneta’s September data had not yet shown that shift. Dimerco’s Kathy Liu, vice president of global sales and marketing at Dimerco Express Group, calls the current lull deceptive: “Bookings look quiet right now, but that’s the calm before the door opens.” For shippers, the question is whether any overflow arrives on a lane already running close to 90% load factors.
For the transpacific, the effect is indirect but real. Every widebody freighter that detours or is priced out by fuel is one fewer for Asia–North America, and every new Gulf shock adds a premium to scarce main-deck space. Resilience is no longer a buzzword. It is a pricing input.
“Bookings look quiet right now, but that’s the calm before the door opens.”
Kathy Liu, Dimerco
Tariffs, de minimis and the chip detour
Policy is the other great variable, and the market has learned to absorb it. Rotate chief executive Ryan Keyrouse, reflecting on last year’s disruption, said: “Everybody expected turmoil but everything just shifted and we continued to see growth.” This year the shifts have kept coming. In February, the US Supreme Court struck down the International Emergency Economic Powers Act (IEEPA) tariffs, yet the landscape has hardly calmed. US courts have since confirmed the president’s authority to end the de minimis exemption for low-value imports, and a congressional repeal takes effect next July. For the e-commerce flows that once filled transpacific freighters, the change looks structural.
Two live tariff threads now frame the lane. Dimerco’s October report notes the US–China truce now runs to 10 January 2027, with a reduction framework on about $30 billion of goods still under negotiation, and expects held-back China–US cargo to move ahead of that date. It also flags USTR’s pending Section 301 overcapacity investigation, covering sixteen economies including China, Taiwan, South Korea, Singapore, Malaysia, Thailand and Vietnam, with semiconductors and electronics among the named sectors.
Semiconductors face their own rules. In January, Washington imposed a 25% tariff on a narrow set of advanced chips, exempting those bound for US data centres, and required certain China-bound chips to pass through the US for third-party testing. For air cargo, that means compliance-heavy routings between Taiwan, the US and China, and a reminder that the AI cargo boom sits where industrial policy meets logistics.
The commercial response is visible in contracts. September’s global spot rate averaged $3.10 per kg, up 27% year on year, according to Xeneta, which says shippers increasingly want floating mechanisms tied to the all-in rates airlines charge forwarders rather than relying on traditional fuel surcharges. The fixed annual deal is giving way to something more flexible.
More than airport to airport
The operators winning this business are selling more than space. DHL Global Forwarding has argued that as AI infrastructure scales, the differentiator is orchestrating the full chain: air and ocean freight, warehousing, customs management, specialised handling and deployment support, rather than capacity alone. It is a reminder that, on a lane this tight, how cargo is handled may matter as much as whether there is space for it.
The return leg
Most of the transpacific story is told in one direction, from Asia to North America. The return leg is thinner and more mixed. WorldACD recorded September tonnage from North American origins up 10% year on year, in line with Asia Pacific, yet in mid-August North America–Asia Pacific tonnage fell 6% week on week. IATA found North American carriers posting the strongest regional demand growth in August, at 6.6%, even as they trimmed capacity by 2.5%. Dimerco’s October forecast rates air space from Los Angeles, San Francisco and New York to Asia as tight with rising rates, and Chicago as backlogged. Within the Americas, Aevean’s January figures showed North America–South America capacity up 16%, a reminder that North American cargo flows run north–south as much as east–west.
What remains unclear is how much of North America’s export strength travels on the same freighters that deliver Asia’s AI hardware, and how directional imbalance shapes yields on the way back. It is a question the available data does not yet answer.
A Kuehne+Nagel employee inspects a semiconductor shipment at one of the company’s warehouses in Amsterdam (Photo: Kuehne+ Nagel)
Questions the industry must answer
Xeneta expects global demand growth of about 4% this year, ahead of early-year expectations, yet still anticipates a muted peak season. That contrast between a soft global picture and a tight lane carrying the AI build-out is the central tension as the year-end peak approaches.
Three questions follow. First, is AI demand structural? Data-centre investment is driven by capital spending rather than consumer sentiment, and the lane’s fortunes now depend on it. Second, who funds the new main-deck capacity? Freighters remain the main source of incremental lift, and manufacturer output and conversion feedstock are both limited. Third, will shippers get the visibility, flexibility and resilience they want, or will scarce capacity keep pricing power with carriers?
TIACA’s 2026 Sustainability Insights Report found that 95% of respondents say their CEO supports sustainability, a sign that the industry is embedding long-term priorities even as the short-term market whipsaws.
The freighters crossing the Pacific this autumn carry more than electronics. They carry the case for air cargo as logistics’ fastest adapter to disruption. How long that advantage lasts depends on the answers to the questions above.
The article was originally published in the October 2026 issue of The STAT Trade Times.
Editor at STAT Publishing Group since 2013, I lead a small team of reporters in chasing stories about cargo flows from A to Z—by air, sea, road, and rail. If it moves, we track it. Got a compelling lead? Reach me at reji@statpublishinggroup.com (cargo only, please)


